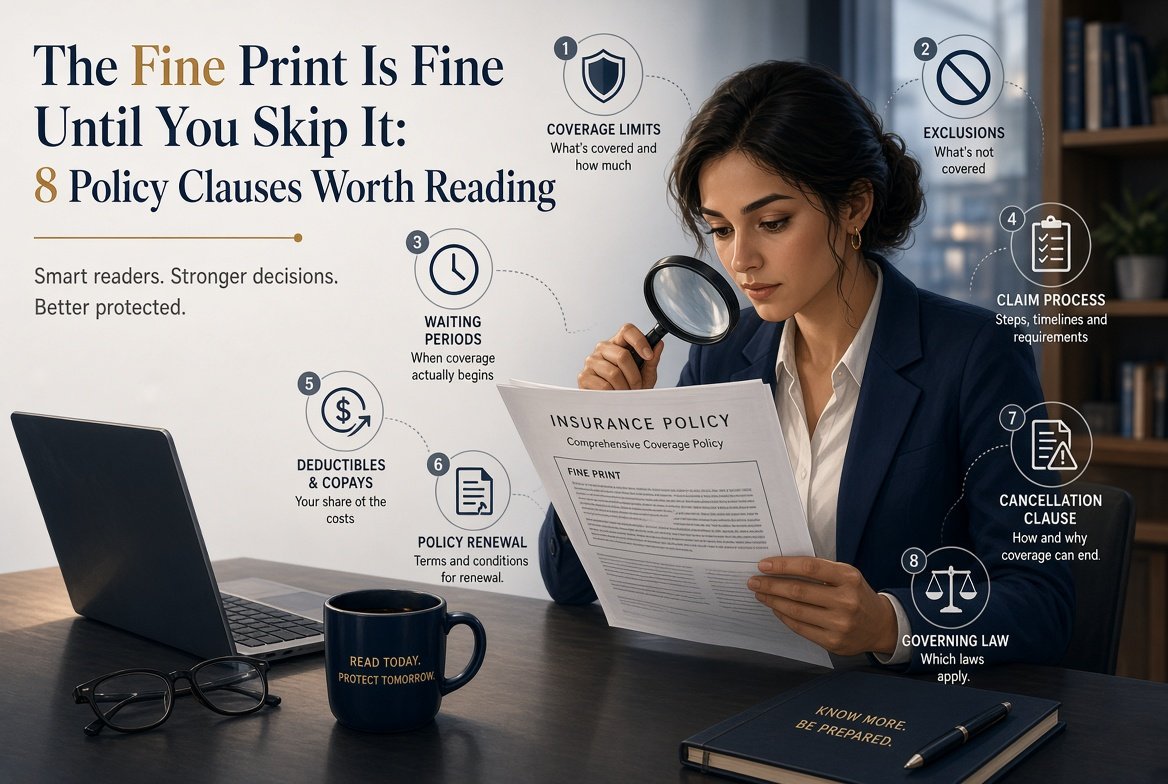
Most people read the premium and coverage amount before buying health insurance. The smaller terms often get less attention. Yet those terms decide when you can claim, which bills are covered and how much you may need to pay yourself.
A policy can look suitable at first glance but work differently during a hospital stay. Before paying, spend a little time with its conditions. These eight clauses deserve a closer look because each can affect your medical bills and claims.
Waiting Period Clause
A waiting period is the time you must complete before certain treatment costs become eligible for cover. Different rules apply to illnesses and procedures. This matters when buying health insurance for parents, especially if treatment may be needed soon.
- Initial waiting period: Find out when cover for illnesses begins.
- Treatment-specific waiting period: Identify procedures with separate waiting rules.
Accidental injuries may be treated differently, depending on policy conditions.
Pre-Existing Disease Clause
An illness diagnosed or treated before you bought the policy may count as a pre-existing disease. Accurate disclosure helps insurers assess applications and avoid claim disputes.
- Medical history: Report conditions, medicines and previous treatment honestly.
- Coverage start: Find out when an accepted condition becomes eligible for claims.
Never assume a disclosed illness is covered immediately. Read any special terms mentioned in the policy schedule.
Exclusions and Limitations
Not every medical expense is covered. An exclusion identifies treatments or situations the insurer will not pay for, while a limitation restricts particular benefits. Your health insurance policy details should explain both clearly.
- Excluded expenses: Identify treatments, services or non-medical items outside cover.
- Restricted benefits: Identify any conditions attached to listed services.
These terms show what you may fund yourself, even with active cover.
Room Rent and Sub-Limits
Some policies restrict your room category or daily charge. Sub-limits cap expenses despite your overall sum insured. Compare this limit with room prices at hospitals you might use.
- Room eligibility: Confirm which room types fall within your cover.
- Expense limits: Look for separate caps on particular procedures or hospital charges.
A higher room category can increase your share of related costs. Understand this before hospital admission.
Co-Payment Clause
A co-payment means you pay an agreed portion of an admissible claim while the insurer pays the remaining eligible amount. It may apply by age, hospital or treatment.
- Your share: Find out when co-payment applies and how it is calculated.
- Exceptions: Look for services where a different condition applies.
A lower premium may come with a larger contribution from your pocket during claims.
Deductibles and Out-of-Pocket Costs
A deductible is what you pay before insurance contributes to an eligible claim. It is different from a co-payment, which shares an eligible expense.
- Deductible amount: Check whether it applies per claim or across the policy period.
- Other expenses: Budget for non-payable items and costs above policy limits.
A large deductible can make smaller hospital bills entirely yours. Together, these charges show what insurance may pay.
Claim Filing and Documentation Requirements
Eligible bills still need the right claim process. Your policy lists notification steps and documents for cashless or reimbursement claims.
- Claim notification: Identify the contact details and applicable reporting timelines.
- Documents: Keep discharge papers, prescriptions, bills and payment receipts as required.
Cashless approval is not automatic. Ask the hospital’s insurance desk for assistance, but keep copies of everything you submit.
Policy Renewal and Cancellation Terms
Renewal rules affect whether cover continues uninterrupted. Cancellation terms explain ending a policy and possible refunds.
- Renewal: Note the due date, grace period and conditions for continued coverage.
- Cancellation: Understand the process, any applicable deductions and refund conditions.
Missing renewal deadlines can affect benefits linked to uninterrupted coverage. Keep your contact details updated for policy communications.
Conclusion
A health insurance policy is more than its premium and sum insured. Waiting periods decide when cover begins, exclusions explain what stays outside it, and cost-sharing clauses show what you may pay yourself. Claim and renewal conditions matter just as much. Before buying or renewing, read the policy wording and Customer Information Sheet. When clauses are unclear, request explanations in writing. That small step can prevent confusion when claims arise.